


Quick Summary
An Initial Coin Offering (ICO) is a blockchain-based fundraising method in which a company or project sells newly created digital tokens to the public, usually in exchange for established cryptocurrencies such as Bitcoin or Ethereum (and increasingly stablecoins). The funds raised are typically used to finance product development, often before the token has a working use case. It is the crypto industry’s rough equivalent of an Initial Public Offering (IPO), except investors receive tokens instead of company equity
That covers the basics. If you are a founder evaluating whether to run one, an investor assessing the risk, or simply someone who wants to understand how this piece of crypto history shaped today’s token economy, you need the full picture, including where ICOs stand legally in 2026, particularly in India. This guide covers all of it.
Key Takeaways
- An ICO sells tokens, not company equity; you are usually buying future utility or access, not ownership.
- Regulatory treatment depends on substance, not labeling: a “utility token” can still be treated as a security if it behaves like an investment contract.
- ICOs carry meaningfully fewer investor protections than regulated offerings; scams and failed projects remain common.
- In India, crypto is legal to hold and trade as a Virtual Digital Asset (VDA), but ICO-related activity faces heightened FIU-IND scrutiny and is strongly discouraged under current AML/CFT guidelines.
- Liquidity after a successful sale is never guaranteed. Rules in this space change quickly treat every regulatory statement in this article as a snapshot as of September 2026 and verify current requirements before acting.
Table of Contents
- What Is an ICO? A Clear Definition
- How Does an ICO Actually Work?
- A Brief History: From Mastercoin to the 2017 Boom and Bust
- Types of Tokens Sold in ICOs
- ICO vs IEO vs STO vs IDO: What’s the Difference?
- Benefits of ICOs
- Risks and Red Flags Investors Should Know
- Are ICOs Legal? Global and Indian Regulatory Status (2026)
- How to Evaluate an ICO Before Investing
- How to Launch a Compliant Token Sale in 2026
- Frequently Asked Questions
What Is an ICO? A Clear Definition
An Initial Coin Offering (ICO) is a crowdfunding mechanism native to blockchain technology. A project team creates a new cryptocurrency token, defines what that token does within its ecosystem, and sells a portion of the token supply to early backers typically before the underlying product, platform, or blockchain network is fully built.
In exchange for their contribution, investors receive tokens that may later be used to:
- Access a product or service (utility tokens)
- Vote on protocol decisions (governance tokens)
- Represent a stake in future profits or assets (security-like tokens, where permitted)
Unlike an IPO, an ICO does not typically grant equity, voting rights on a company’s board, or dividends. This is the single most important distinction for beginners to understand, and it is also the reason regulators worldwide have scrutinized ICOs so closely; a token that behaves like an investment contract may legally be a security, regardless of what the project calls it.
How Does an ICO Actually Work?
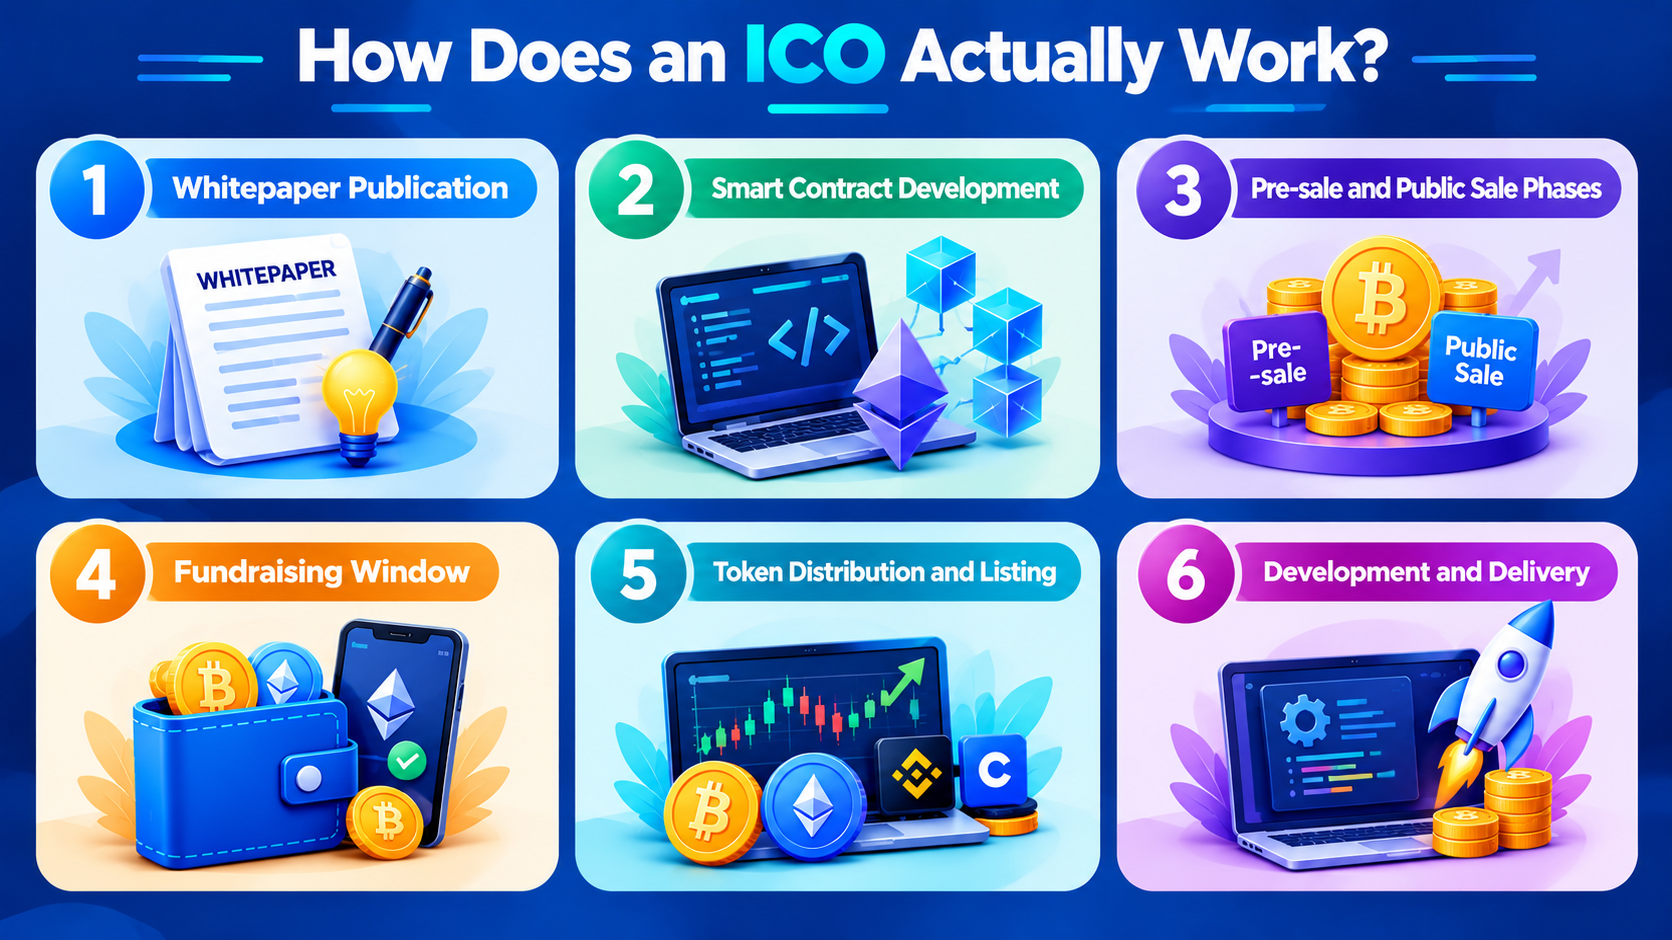
A typical ICO follows a fairly consistent lifecycle:
- Whitepaper publication. The team releases a whitepaper explaining the problem being solved, the technology, the token’s utility, the tokenomics (total supply, allocation, vesting schedule), and the roadmap.
- Smart contract development. The token is usually built as a smart contract on an existing blockchain (historically Ethereum’s ERC-20 standard, though Solana, BNB Chain, and Layer-2 networks are common today) rather than on a brand-new blockchain.
- Pre-sale and public sale phases. Many projects run a private/pre-sale round for early backers and venture investors at a discounted price, followed by a public sale open to retail participants.
- Fundraising window. Contributors send crypto (or fiat via on-ramps) to a smart contract address during a defined window and receive tokens in return, often on a fixed or tiered price schedule.
- Token distribution and listing. Once the sale concludes, tokens are distributed to contributors’ wallets, and the project typically seeks a listing on one or more cryptocurrency exchanges to create secondary-market liquidity.
- Development and delivery. The raised funds are meant to be used to build the product described in the whitepaper; this is the stage where the gap between promise and execution becomes visible.
A Brief History: From Mastercoin to the 2017 Boom and Bust
Understanding ICO history helps explain both their appeal and the regulatory backlash that followed.
- 2013: Mastercoin (later rebranded Omni) is widely credited with running the first token sale, raising roughly 5,000 BTC.
- 2014: Ethereum itself was funded through a token sale, raising around $18 million proving the model could fund foundational infrastructure, not just applications.
- 2016: The DAO, a decentralized venture fund built on Ethereum, raised over $150 million before being exploited in a hack that led to Ethereum’s contentious hard fork.
- 2017: The ICO boom exploded. Projects collectively raised billions of dollars over the year, with some sales completing in minutes. This period also produced widespread scams, “rug pulls,” and wildly unrealistic whitepapers with no working product behind them.
- 2017-2018: Regulators responded. The U.S. SEC’s DAO Report concluded that certain tokens qualified as securities under the Howey Test. China and South Korea banned ICOs outright. Other jurisdictions began drafting dedicated frameworks.
- 2019 onward: As enforcement tightened, the market shifted toward more compliant fundraising structures; IEOs, STOs, and later IDOs, which we cover below.
This history matters for one practical reason: most serious projects now build legal counsel, jurisdictional analysis, and (where applicable) securities-law exemptions into the process from the outset, rather than treating them as an afterthought.
Types of Tokens Sold in ICOs
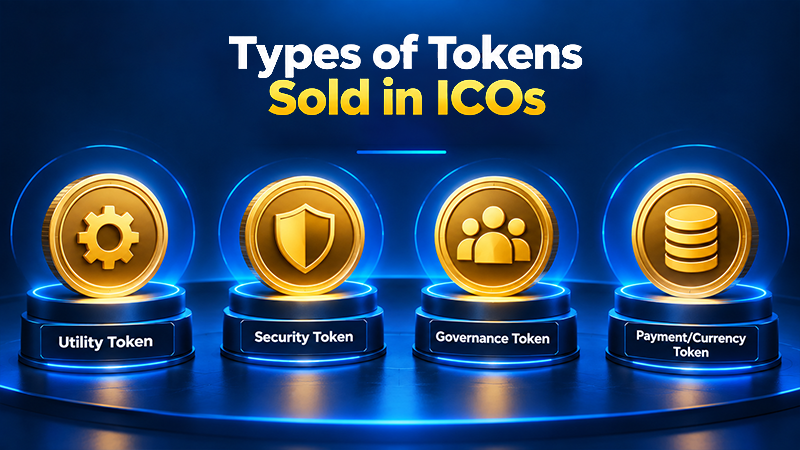
Not all tokens sold in an ICO are the same. The classification affects both the regulatory treatment and the investor’s actual rights.
| Token Type | What It Represents | Regulatory Risk |
|---|---|---|
| Utility Token | Access to a future product/service on the platform | Lower, if genuinely functional and not marketed as an investment |
| Security Token | Ownership, profit-share, or debt-like claim | High, generally regulated as a security |
| Governance Token | Voting rights over protocol parameters | Moderate, depends on how it is marketed and distributed |
| Payment/Currency Token | Medium of exchange within or across networks | Moderate, may attract money-transmission rules |
Regulators, including the U.S. SEC, generally apply a substance-over-form test: what matters is whether buyers reasonably expect profit from the efforts of others (the core of the Howey Test), not what label the whitepaper uses. Even tokens marketed purely as “utility” tokens can be recharacterized as securities if there is no live functioning product at the time of sale and the offering is heavily marketed on price-appreciation potential. The “Regulatory Risk” column above is a general guide only, not a guarantee.
ICO vs IEO vs STO vs IDO: What’s the Difference?
Since 2019, ICOs have largely been supplemented and in many markets replaced by better-structured alternatives. IEOs and IDOs in particular offer built-in exchange vetting and near-instant secondary-market liquidity that a standalone ICO cannot guarantee on its own. Here’s how they compare:
| Model | Full Form | Where It Happens | Key Difference from ICO |
|---|---|---|---|
| ICO | Initial Coin Offering | Project’s own website/smart contract | No intermediary vetting; highest flexibility, highest risk |
| IEO | Initial Exchange Offering | Directly on a crypto exchange | Exchange vets and lists the project, adding a layer of due diligence |
| STO | Security Token Offering | Regulated securities platforms | Token is explicitly structured and registered as a security |
| IDO | Initial DEX Offering | Decentralized exchange (DEX) launchpad | Instant liquidity via automated market makers; permissionless |
If you are a founder in India in 2026, this comparison is practical: it directly affects which regulator(s) you may fall under (primarily FIU-IND for AML, potentially SEBI for securities-like characteristics, or others depending on structure) and which compliance obligations apply.
Benefits of ICOs
For founders and startups:
- Access to global capital without traditional VC gatekeeping
- Faster fundraising cycles compared with equity rounds
- Built-in community and early user base
- Generally no direct dilution of company equity, since tokens are not shares, though tokens carrying profit-sharing or governance rights can still create economic or regulatory equity-like obligations
For investors:
- Early access to potentially high-growth projects
- Liquidity potential once tokens list on exchanges
- Participation in genuinely novel infrastructure (e.g., Ethereum’s own ICO)
- Lower minimum investment thresholds than traditional venture capital
Risks and Red Flags Investors Should Know
ICOs carry meaningfully higher risk than regulated securities offerings. Historically they have been far less regulated than IPOs, and even as oversight has tightened in many jurisdictions through 2026, standalone ICOs still offer fewer built-in investor protections. This makes them susceptible to fraud. Investors may be drawn in either by genuine interest in future utility or by the hope of price appreciation.
Common red flags include:
- Anonymous or unverifiable teams with no track record or LinkedIn presence
- Guaranteed returns or “risk-free” language, a hallmark of scams
- Unrealistic roadmaps with no working prototype or GitHub activity
- Excessive token allocation to founders/insiders with little or no vesting
- No third-party smart contract audit
- Celebrity endorsements used as the primary credibility signal rather than substance
- Pressure tactics countdown timers, “limited slots,” and urgency-driven marketing
Even a well-run ICO offers no guarantee of secondary-market liquidity. A token can complete its sale successfully and still fail to secure a meaningful exchange listing, leaving contributors unable to exit.
Regulators caution that investors should approach ICOs with extreme caution: they carry considerably fewer investor protections than traditional securities markets, and total loss of investment is possible.
Are ICOs Legal? Global and Indian Regulatory Status (2026)
Short answer: ICOs are not banned in most major economies, but they are increasingly regulated. The specific rules depend heavily on jurisdiction and how the token is structured. Details below reflect the landscape as of September 2026 and can change with little notice.
Global landscape
- United States: No single ICO-specific statute exists. Several agencies (primarily the SEC, CFTC, and state regulators) play active roles. Depending on structure, an ICO can fall under securities law, commodities rules, or money-transmission requirements.
- Switzerland: FINMA maintains one of the more mature frameworks. ICOs are treated as a means of raising capital via blockchain, where investors typically receive a token connected to a right (dividend, voting right, license, or claim on the issuer’s future performance).
- China: Continues to maintain its 2017 ICO ban, with no confirmed change as of this writing.
- South Korea: Domestic ICOs have been prohibited since 2017 and the ban remains in force. In January 2026 the Financial Services Commission finalized guidelines allowing listed companies and certain professional investors to invest in crypto (subject to limits). This is a separate policy from the domestic ICO ban itself, which has been the subject of industry discussion and draft proposals but has not been lifted. Treat any claim that “South Korea has legalized ICOs” with caution until an official notification is published.
India’s 2026 regulatory framework
India’s stance has matured considerably since the RBI’s 2018 banking restrictions (struck down by the Supreme Court in 2020). As of September 2026:
- Crypto assets are legally classified as Virtual Digital Assets (VDAs). Holding, buying, and selling crypto is legal, but crypto is not legal tender.
- Gains are subject to a flat 30% tax with no loss offset. A 1% TDS applies under the relevant provisions (commonly referenced as Section 194S or its successor under the Income-tax Act, 2025). The current thresholds are ₹50,000 in aggregate annual consideration for specified persons (most individuals and HUFs) and ₹10,000 for others. The rate rises to 20% if the seller has not furnished a PAN. These thresholds and procedural details are set by notification and can change, so confirm the figures in force at the time of any transaction.
- India operates a multi-regulator approach. FIU-IND is the primary body for AML/CFT compliance for Virtual Digital Asset Service Providers (VDASPs). SEBI may scrutinize offerings that resemble securities or involve investor-protection concerns. Tax reporting and oversight sit with the CBDT.
- Registration and compliance obligations for platforms serving Indian users are activity-based rather than purely location-based. Offshore platforms serving Indian users generally fall under the same PMLA framework. Registered entities are expected to designate a Designated Director and Principal Officer and maintain a written AML/CFT compliance program.
- Under FIU-IND’s updated AML & CFT Guidelines for Reporting Entities Providing Services Related to Virtual Digital Assets (issued 8 January 2026), ICO/ITO-related activities are described as presenting heightened ML/TF/PF risks and are strongly discouraged. Persons offering services related to issuance, sale, distribution, or ongoing trading of such tokens may fall within the reporting-entity framework and are expected to perform robust risk assessments and controls. Reporting entities are required to refrain from facilitating deposits or withdrawals of anonymity-enhancing crypto tokens (privacy coins) and from transactions involving mixers, tumblers, or similar tools designed to obscure origin, ownership, or value.
Practical takeaway for Indian founders: Running an ICO targeting Indian users in 2026 without thorough SEBI/FIU-IND compliance review and qualified legal counsel creates significant legal exposure. Treat “utility token” labeling as only the starting point for legal analysis, not a shield.
(This section is for general informational purposes only and is not legal or financial advice. Regulations evolve quickly, so verify current requirements with a licensed professional before acting.)
How to Evaluate an ICO Before Investing
Use this checklist before committing funds to any token sale:
- Read the whitepaper critically – does it explain a real problem and a technically sound solution, or is it vague and buzzword-heavy?
- Verify the team – real names, real history, verifiable prior work.
- Check for a smart contract audit from a reputable firm (e.g., CertiK, Trail of Bits, Hacken) and read the actual findings, not just the badge.
- Review tokenomics – total supply, allocation split, vesting schedules for founders/team.
- Look for existing product traction – GitHub commits, testnet activity, working demos.
- Confirm legal structure – entity registration, jurisdiction, and applicable regulatory disclosures.
- Assess community quality, not just size – genuine technical discussion beats bot-inflated follower counts.
- Never invest more than you can afford to lose entirely.
How to Launch a Compliant Token Sale in 2026
For founders considering a token launch today, the market has moved well past “whitepaper and a Telegram group.”
A credible 2026 launch typically includes:
- Legal structuring and jurisdictional analysis (including securities-law exemption pathways where applicable)
- Smart contract development and independent audit
- Tokenomics design aligned with long-term incentive alignment, not just fundraising maximization
- KYC/AML infrastructure for contributor onboarding
- A realistic technical roadmap with milestones tied to fund release (rather than a single lump-sum raise)
- A go-to-market and exchange-listing strategy planned well before the sale, not after
None of this guarantees regulatory compliance on its own. Jurisdictional rules for token sales are jurisdiction-specific, actively evolving, and ultimately require sign-off from qualified legal counsel, not a checklist. What a technical partner can do is ensure the smart contract, tokenomics, and audit trail are built correctly from day one, so your legal counsel has a sound technical foundation to assess rather than a retrofit.
Frequently Asked Questions
Is an ICO the same as an IPO?
No. An IPO sells company equity through a regulated stock exchange. An ICO sells blockchain-based tokens that usually grant product utility, not ownership, and typically involve far fewer investor protections.
Are ICOs still happening in 2026?
Yes, though the market increasingly favors IEOs, IDOs, and compliant STO structures that offer more built-in vetting and regulatory clarity than a standalone ICO.
Can Indian citizens legally invest in ICOs?
Buying and holding crypto assets is legal in India as VDAs. Gains are taxed at a flat 30% with 1% TDS on qualifying transactions, and platforms serving Indian users face FIU-IND (and potentially other) compliance obligations. Always verify a platform’s registration status and regulatory posture before participating.
How do I know if a token is a security?
Regulators generally look at substance over labeling. If buyers are investing money in a common enterprise expecting profits primarily from the efforts of others, the token is likely to be treated as a security regardless of what the whitepaper calls it.
What’s the safest way to evaluate an ICO?
Verify the team, read the smart contract audit, understand the tokenomics and vesting terms, and confirm the project’s legal/regulatory posture before contributing any funds.
What happens to my funds if an ICO project fails or the team disappears?
In most cases, very little can be recovered. Because ICOs typically are not structured with the investor protections of regulated securities offerings, there is often no equivalent of bankruptcy proceedings, escrow-backed refunds, or a regulator you can easily appeal to, particularly if the team is anonymous or based outside your jurisdiction. This is why due diligence before contributing matters far more than after something goes wrong.
Do Indian investors need to report ICO/crypto income separately at tax time?
Yes. Gains from Virtual Digital Assets are reported under the relevant VDA schedule in the income-tax return, taxed at a flat 30%, with any TDS already deducted claimable as credit against final liability. This is general information, not tax advice, so consult a chartered accountant familiar with VDA reporting for your specific situation.
Thinking About Launching a Token or ICO?
Building a compliant, technically sound token offering requires more than a whitepaper; it requires smart contract engineering, tokenomics design, and regulatory-aware architecture from day one.
Coin Developer India helps founders design, audit, and launch blockchain-based fundraising solutions, from ICO and IDO smart contracts to full tokenomics consulting. If you are evaluating a token launch or need a technical and compliance review of an existing project, get in touch with our team for a free initial consultation.
Disclaimer: This article is for educational purposes only and does not constitute financial, investment, or legal advice. Cryptocurrency investments are high-risk and regulations vary by jurisdiction and change frequently. Always consult a qualified financial advisor and legal counsel before participating in or launching a token offering.